How to Choose a US Stock Data API: What Is Worth Paying for, from Daily Backtests to Premarket Monitoring?
TickDB Research ·
How to Choose a US Stock Data API: What Is Worth Paying for, from Daily Backtests to Premarket Monitoring?
Abstract: For small teams using Python to backtest US stocks and maintain research watchlists, this guide compares yfinance, Alpha Vantage and TickDB. Official documentation and a real archived snapshot show when an existing free workflow is sufficient, which premarket requirements may justify paid access, and what to verify before a trial. The aim is to connect data capabilities, access conditions and integration work to an actual research task.
Your team already downloads daily US stock data through yfinance. After the close, a script screens stocks and produces a research watchlist. Now the team wants to check that list before the next opening bell.
Keep the existing research library while checking the new requirement. If request settings solve it, change those settings; if a premarket object is already present, read that object. Compare paid access when an essential historical range, data time or use condition remains unmet.
This guide starts with a working daily-data workflow and evaluates an additional premarket requirement.
Starting with “free versus paid” skips the questions that decide whether either approach will work. Does the request include extended hours? What data freshness does the account provide? Which session does the displayed price describe?
One finding matters before discussing a replacement: yfinance documents extended-hours options and streaming interfaces. Identify the missing requirement first, then decide where to spend engineering time and budget.
1. What actually changes when research moves into the premarket?
An end-of-day screen and a live premarket watchlist may use the same symbols, but they need different inputs.
Daily history helps identify candidates. Intraday history helps examine an earlier earnings reaction. Monitoring now requires the relevant session quote, its timestamp and an appropriate update mechanism. These are separate requirements.
| Task | Required input | First selection question |
|---|---|---|
| End-of-day research and daily backtesting | Historical prices for specified symbols and dates, with an explicit adjustment basis | Can the required range and price basis be obtained under the access conditions? |
| Reviewing an earlier premarket event | Intraday observations covering that date and session | Are the interval, extended hours and lookback suitable? |
| Monitoring premarket activity now | A quote for the relevant session, its time and subsequent updates | Do freshness, entitlement and delivery fit the task? |
Streaming may be irrelevant to the first task. It becomes a real consideration in the third. The trial should reflect that change instead of repeating a successful daily download.
2. Which of the three paths should the team try first?
The candidates here are Yahoo Finance accessed through yfinance, Alpha Vantage and TickDB. They are a shortlist for this decision, not an exhaustive market ranking.
Keep yfinance in consideration if the workflow already works
yfinance is an open-source Python tool for accessing Yahoo Finance data. It should not be treated as an official Yahoo service commitment. The project documents historical downloads as well as WebSocket and AsyncWebSocket interfaces.
For a team with working scripts, inspect the existing route before replacing it. The download interface has prepost disabled by default. Premarket research therefore calls for checking that option, the intraday interval and the history actually returned.
If the result meets the research requirement, preserving the workflow has value. A free tool does not itself grant additional rights to the underlying data; the project notes personal-use considerations, so the team must check its intended use against the applicable terms.
Evaluate Alpha Vantage at the function and entitlement level
Alpha Vantage offers time-series and indicator interfaces. Those are reasons to consider it when the project needs those inputs, but access depends on the actual function and entitlement.
Its intraday documentation includes extended hours by default. Freshness is separately controlled through entitlement; without that setting, historical data is returned. The intraday function is marked as a premium endpoint, with additional conditions for real-time access.
As checked on November 16, 2026, the standard allowance is 25 requests per day. That helps plan a trial; it does not establish access to a particular endpoint or to real-time data.
Test TickDB against the combined history and quote task
TickDB’s US stock data API provides historical bars, quote snapshots and streaming access for quantitative research and financial applications. A team adding premarket observations can test historical and session-specific inputs within one integration route. On the market page, first inspect extended-hours quote objects, fixed-range access conditions and the corresponding request examples.
The conditions matter. Current K-line documentation says free access does not support specifying historical start and end times. A fixed-range research request therefore requires checking the corresponding permission first. Extended-hours quote availability also depends on the supported instrument and available data.
| Path | Reason to keep it on the shortlist | First check |
|---|---|---|
| Yahoo Finance / yfinance | Existing scripts already satisfy much of the research task | Required interval and session, actual data time, intended use |
| Alpha Vantage | The project needs its specific time-series or indicator functions | Function, freshness, entitlement and request allowance |
| TickDB | The team wants to test history and session quotes through one integration route | Fixed-range access, extended-hours objects and subsequent updates |
For the team in the opening example, I would start with two paths.
First check the existing yfinance workflow. If its intervals, extended-hours settings, actual timestamps and use conditions meet the new requirement, adding another provider for that same requirement may be unnecessary.
Then test TickDB’s premarket quote path. The archived AAPL response below contains a premarket object. Use that finding to define a fresh trial for the symbols and session the team actually follows. Keep the existing daily research library while evaluating the new input; a wholesale migration is a separate decision.
Defer a new Alpha Vantage integration for now. Its additional indicator functions are not yet a requirement for this watchlist. If the team already uses Alpha Vantage, the order changes: inspect its intraday function and entitlements before introducing another integration.
This is a trial order based on the existing workflow, not a claim about overall provider quality. yfinance and Alpha Vantage are assessed from their official materials here; the next section examines an actual TickDB response.
3. A premarket quote can be present while the page still shows yesterday
An AAPL.US snapshot captured around 04:22 US Eastern time on November 4, 2026 contained two price objects.
| Object | Price (USD) | Data time (US Eastern) |
|---|---|---|
Top-level last_price | 331.90 | 2026-11-03 16:00:00 |
pre_market_quote.last_done | 332.10 | 2026-11-04 04:22:25 |
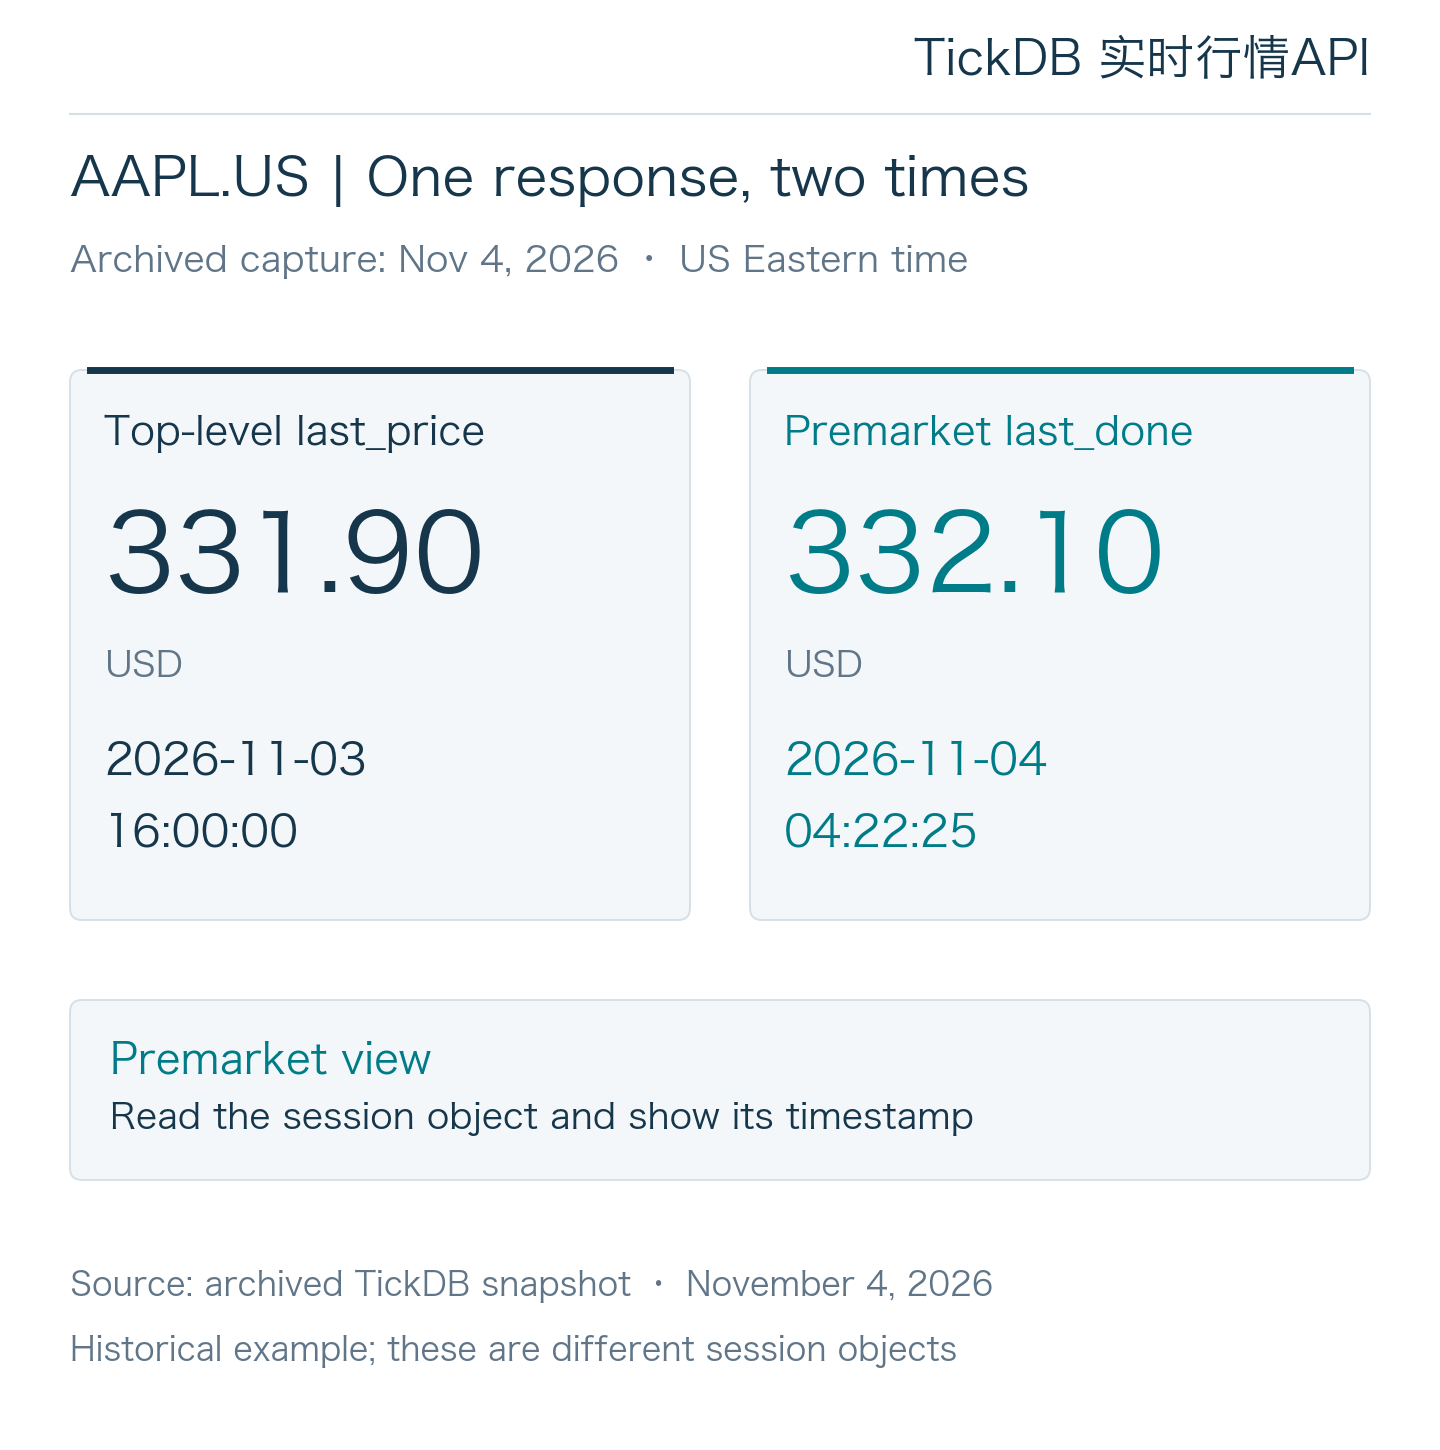
The top-level field is last_price; the premarket field is pre_market_quote.last_done. This is a November 4 historical sample.
If the application reads only the top-level price when the research task concerns November 4 premarket activity, it displays the previous day’s closing record. The response already contains premarket data; the application must select that object and display its corresponding time.
The two values differ by USD 0.20. They come from different objects in one response, not from competing providers. The useful finding is about session selection, not a claimed pricing error or investment loss.
This changes the diagnostic question: is the required input absent, unavailable to the account, excluded by the request, or present in an object the application did not read?
Historical comparisons also require aligned settings. yfinance downloads default to automatically adjusting OHLC; Alpha Vantage’s intraday interface defaults to an adjusted series; TickDB stock bars default to unadjusted prices. Check parameter and methodology details before treating different default outputs as a test of accuracy.
4. Tie spending to a requirement the team actually has
Historical range and resolution
A multi-year daily study and a minute-by-minute earnings review require different history. Specify the symbols, dates, interval and adjustment basis before comparing access. “Long history” alone does not answer whether the necessary interval is available.
Paying for a candidate has a clear purpose when it supplies an essential range or resolution the current workflow cannot obtain.
The session and update conditions needed now
An archived premarket study can be performed after data becomes available. Monitoring now requires suitable freshness and delivery.
Ask whether the candidate provides the relevant quote during the target session under the required access conditions. Request counts alone will not answer that question, and extended-hours coverage does not by itself establish real-time access.
Use conditions and integration work
Personal research, an internal team tool and a customer-facing quote page have different intended uses. Check the tool’s license and the underlying data terms separately.
Record integration work during the trial: how much of the existing script is reusable, whether another pipeline is needed, and what documentation or support is available when the inputs differ. That is more informative than assuming one path will be easier to maintain.
Record which modules actually need changes: requests, object parsing, timestamp display or historical inputs. This review did not measure migration hours or quantify savings.
5. Make the trial small enough to produce a decision
Start with the requirement most likely to change the shortlist, such as adding premarket observations to an existing daily watchlist.
| Trial item | Requirement to hand to a technical colleague |
|---|---|
| Task | Add premarket observations for an existing US daily research watchlist, starting with one relevant symbol |
| Historical input | Specify symbol, dates, interval and adjustment basis; record what is actually returned |
| Premarket input | Distinguish historical review from current monitoring; preserve the quote object and Eastern timestamp |
| Access | Record endpoint, entitlement, request settings and intended use |
| Keep testing if | Essential inputs match the instrument, range and session, with a clear path to check remaining conditions |
| Defer or exclude if | A necessary condition remains unmet; identify whether it concerns settings, permissions or capability |
The AAPL material supports a concrete initial decision:
| Item | Decision from this review |
|---|---|
| New requirement | Add premarket observations to a daily watchlist |
| Existing evidence | yfinance documents extended-hours options; the November 4 TickDB snapshot contains an AAPL premarket object |
| First two paths | Inspect the existing yfinance workflow; test TickDB’s quote object and time during the target session |
| Deferred work | A new Alpha Vantage integration and migration of the existing daily research library |
| Next decision | Keep a route if the target session, timestamps and use conditions fit; otherwise investigate the specific missing condition |
| Observation | Next action |
|---|---|
| The request excludes the target session | Check interval, extended-hours settings and actual output |
| A premarket object exists, but the page reads the top-level price | Read the relevant object and display its time |
| A necessary historical range is restricted | Check entitlement or another path before comparing spending |
| Essential conditions are met | Keep the route and expand the watchlist trial |
The snapshot is from November 4, not a measurement of today’s updates. After confirming the retrieval method, expand testing to the real watchlist, required historical ranges and operating sessions.
The budget question becomes concrete: which necessary research requirement does this expense satisfy? Keep the existing route when it fits. Pay for additional data or services when the missing requirement justifies them.
Sources and sample notes
- yfinance README and download documentation, checked November 16, 2026.
- Alpha Vantage API Documentation and Premium API Key information, checked November 16, 2026.
- TickDB snapshot, K-line, WebSocket Ticker and US stock product documentation, checked November 16, 2026.
- AAPL.US sample captured November 4, 2026; the raw response and Eastern-time conversion were rechecked. This article concerns data selection, not securities recommendations.